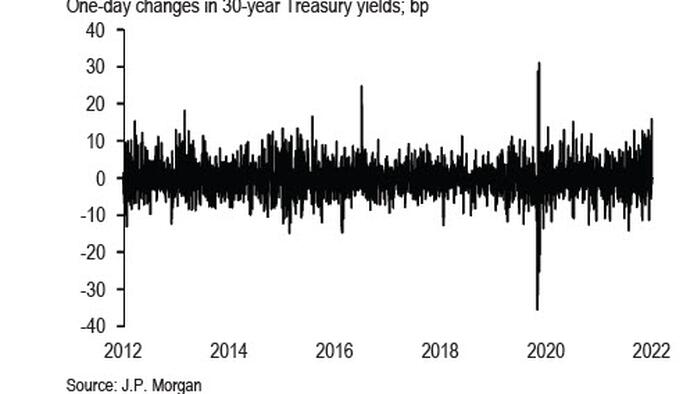
'Extreme' Short in Long-End Treasuries Delivers Volatility Not Seen Since 2020
(Bloomberg) -- A build-up of short positions in long-dated Treasuries has sent ripples through some measures of interest-rate volatility, where daily moves are rivaling those of the March 2020 liquidity crisis.Most Read from BloombergChina Evergrande Group Files Chapter 15 Bankruptcy in New York‘Poor Man’s Cocaine’ Costing $3 a Pill Threatens to ProliferateUS Equities Remain in Retreat as Bonds Rebound: Markets WrapChina’s Hidden Financial Dangers Erupt With Shadow Bank CrisisBitcoin Calm Shatte
Source: yahoo.com