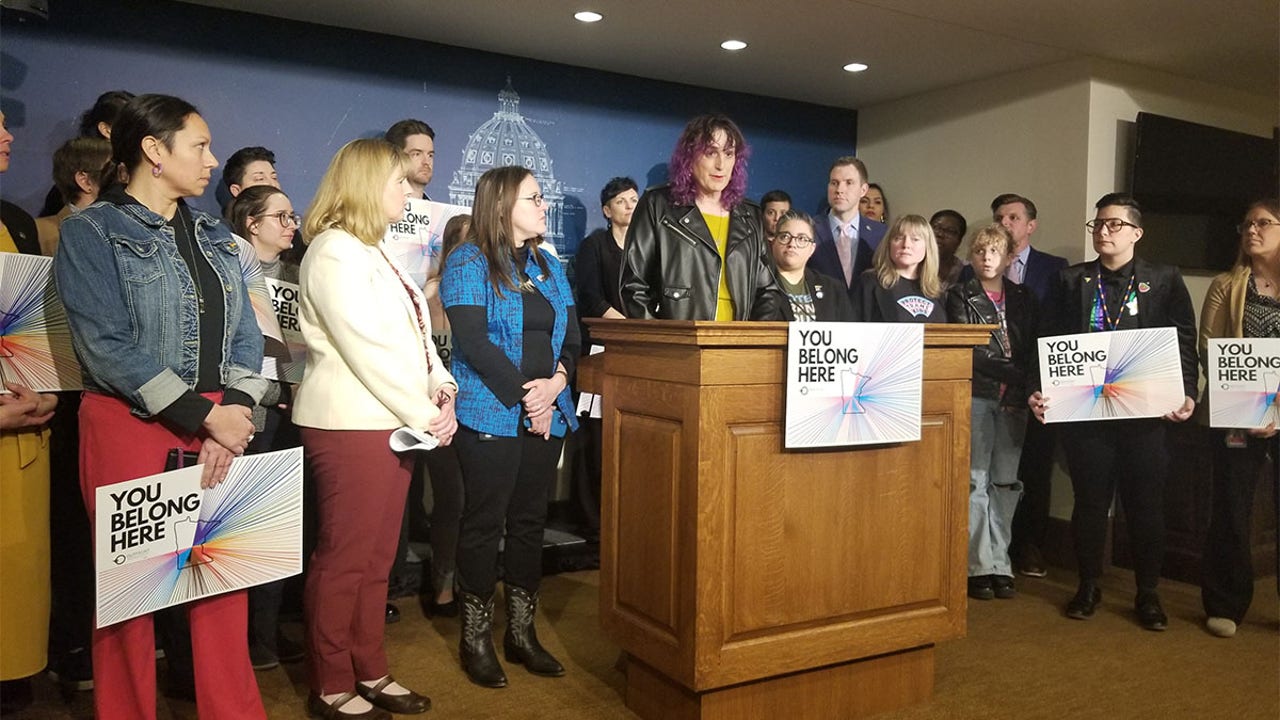What if My Loan is Still with a Bridge Bank? | Seyfarth Shaw LLP
When Signature Bank and Silicon Valley Bank were placed in receivership, the Federal Deposit Insurance Corporation (FDIC) transferred their respective assets to “bridge depository...
Stay updated with breaking news from Enforcement Act. Get real-time updates on events, politics, business, and more. Visit us for reliable news and exclusive interviews.
When Signature Bank and Silicon Valley Bank were placed in receivership, the Federal Deposit Insurance Corporation (FDIC) transferred their respective assets to “bridge depository...
Where a judge enforced a child-custody order from a German court awarding custody of two children to their mother, that decision should be upheld because the Uniform Child-Custody Jurisdiction and Enforcement Act did not require the German court to apply the best-interest factors used in Michigan child custody cases.
Two resort companies in Florida have agreed to pay $325,000 to settle allegations related to false certifications they provided on a Paycheck Protection Program.
Lawmakers in Minnesota are working to ensure transgender youth have a safe space when seeking gender-affirming healthcare, moving a new "Trans Refuge" bill closer to law.
It has long been understood that deposit guarantees and too-big-to-fail (TBTF) policies create a moral-hazard problem—they incentivize banks to take on too much risk by shielding depositors and shareholders from losses in excess of equity (“left-tail” outcomes)—in American banking.1 Congress passed the Federal Deposit Insurance Corporation Improvement Act (FDICIA) in 1991 to mitigate the moral-hazard problem by restricting forbearance and implicit subsidies for undercapitalized banks.