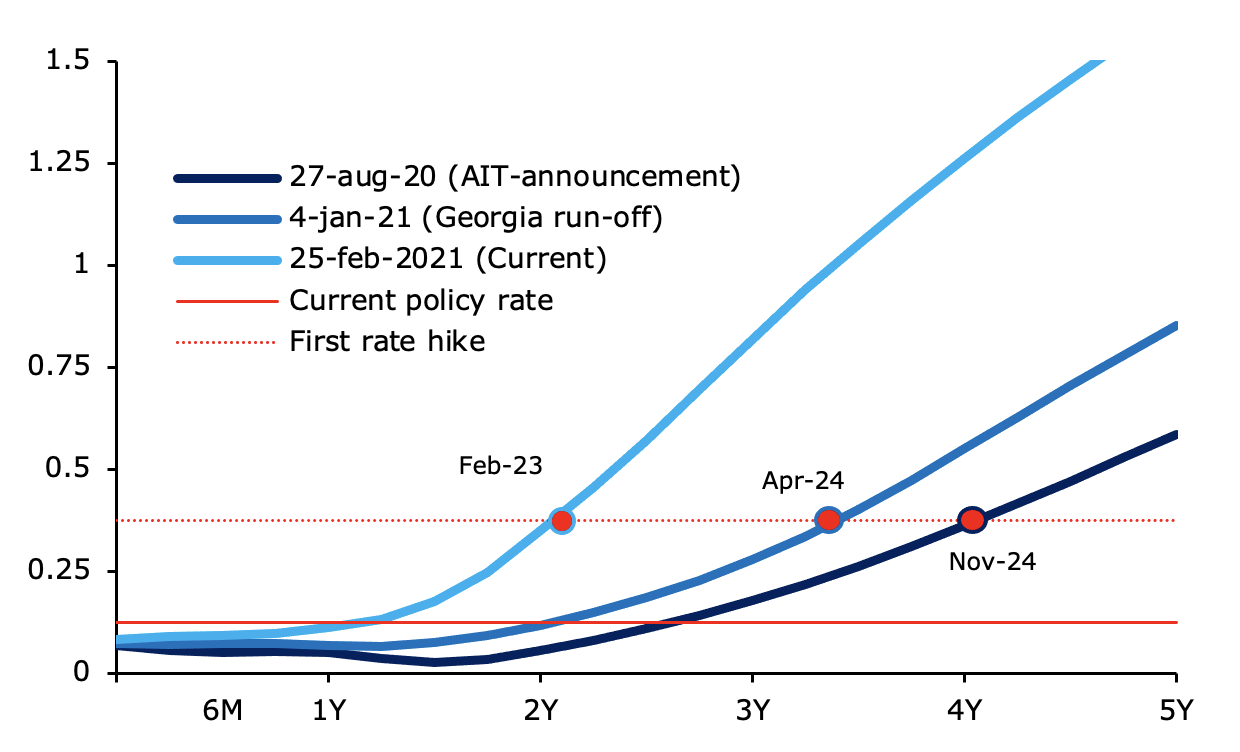
The market-implied effects of the Biden stimulus and the Fed's new policy framework
Itamar Drechsler, Alexi Savov, Philipp Schnabl The slope of the US yield curve, as measured by the spread between 10-year and 2-year rates, currently resides at its steepest level since 2016. The recent steepening is the result of a combination of the Federal Open Market Committee’s (FOMC) commitment to keep front-end rates lower for longer together with upward pressure on the long end due to a brighter economic outlook. The latter is driven by several factors, including the rollout of vaccination programmes, the substantial fiscal accommodation, and the expectation that the Fed will not im...
Source: voxeu.org

